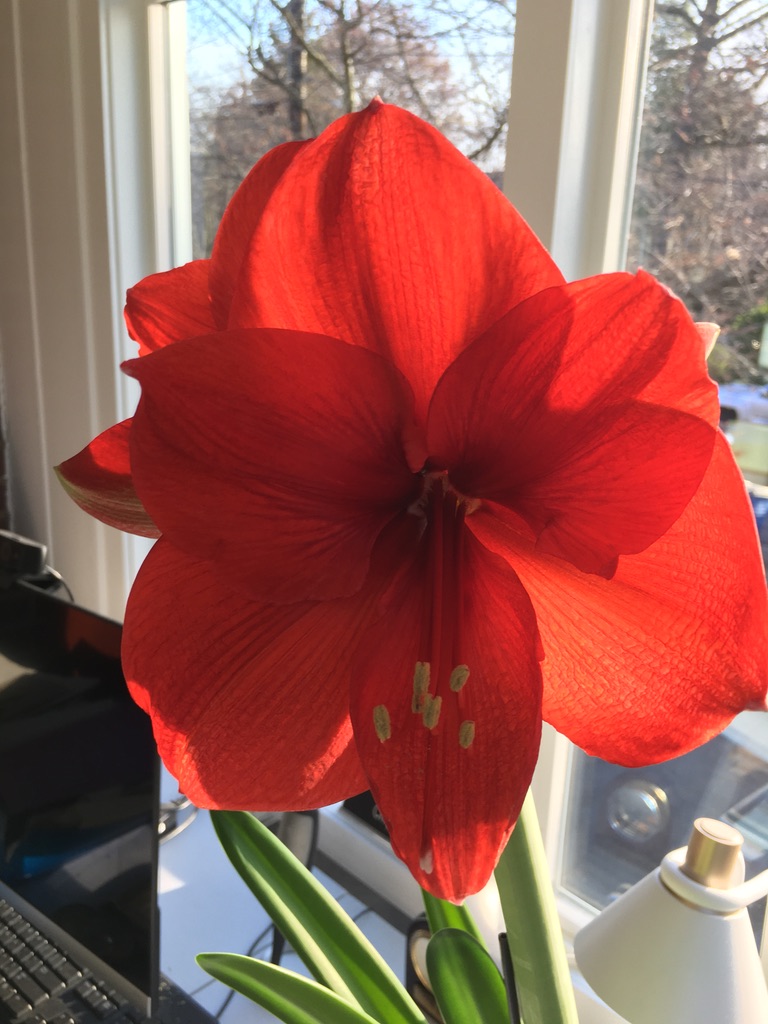
Life Awakens For Ukraine’s Future
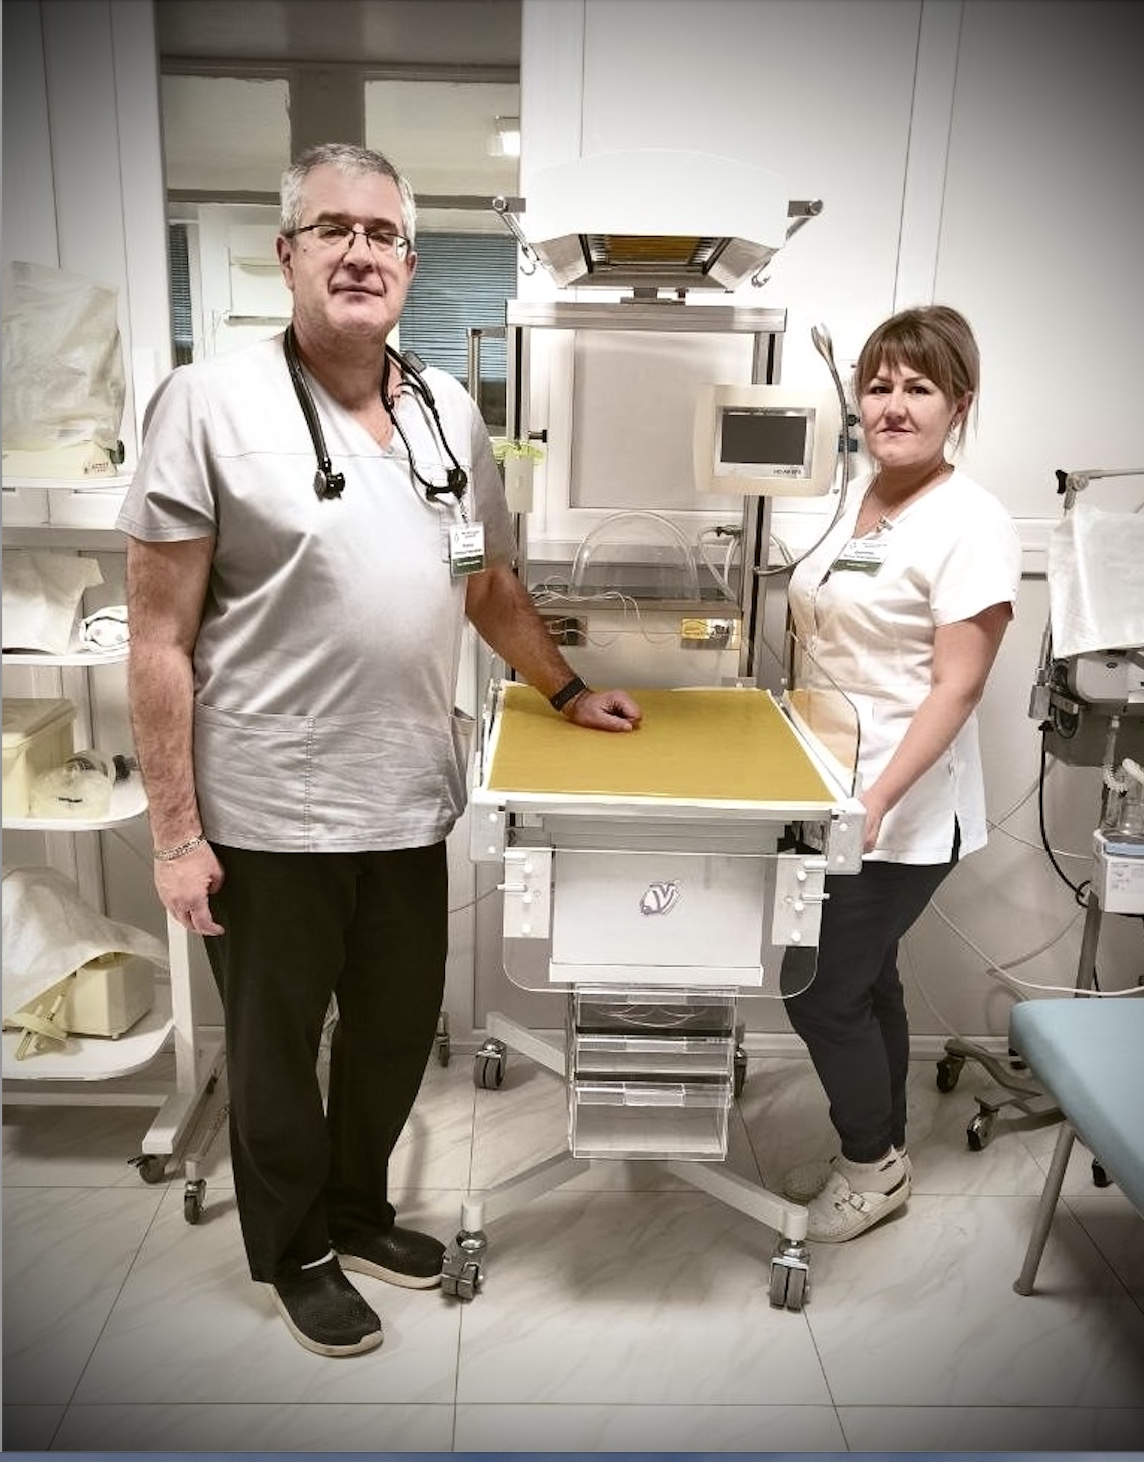
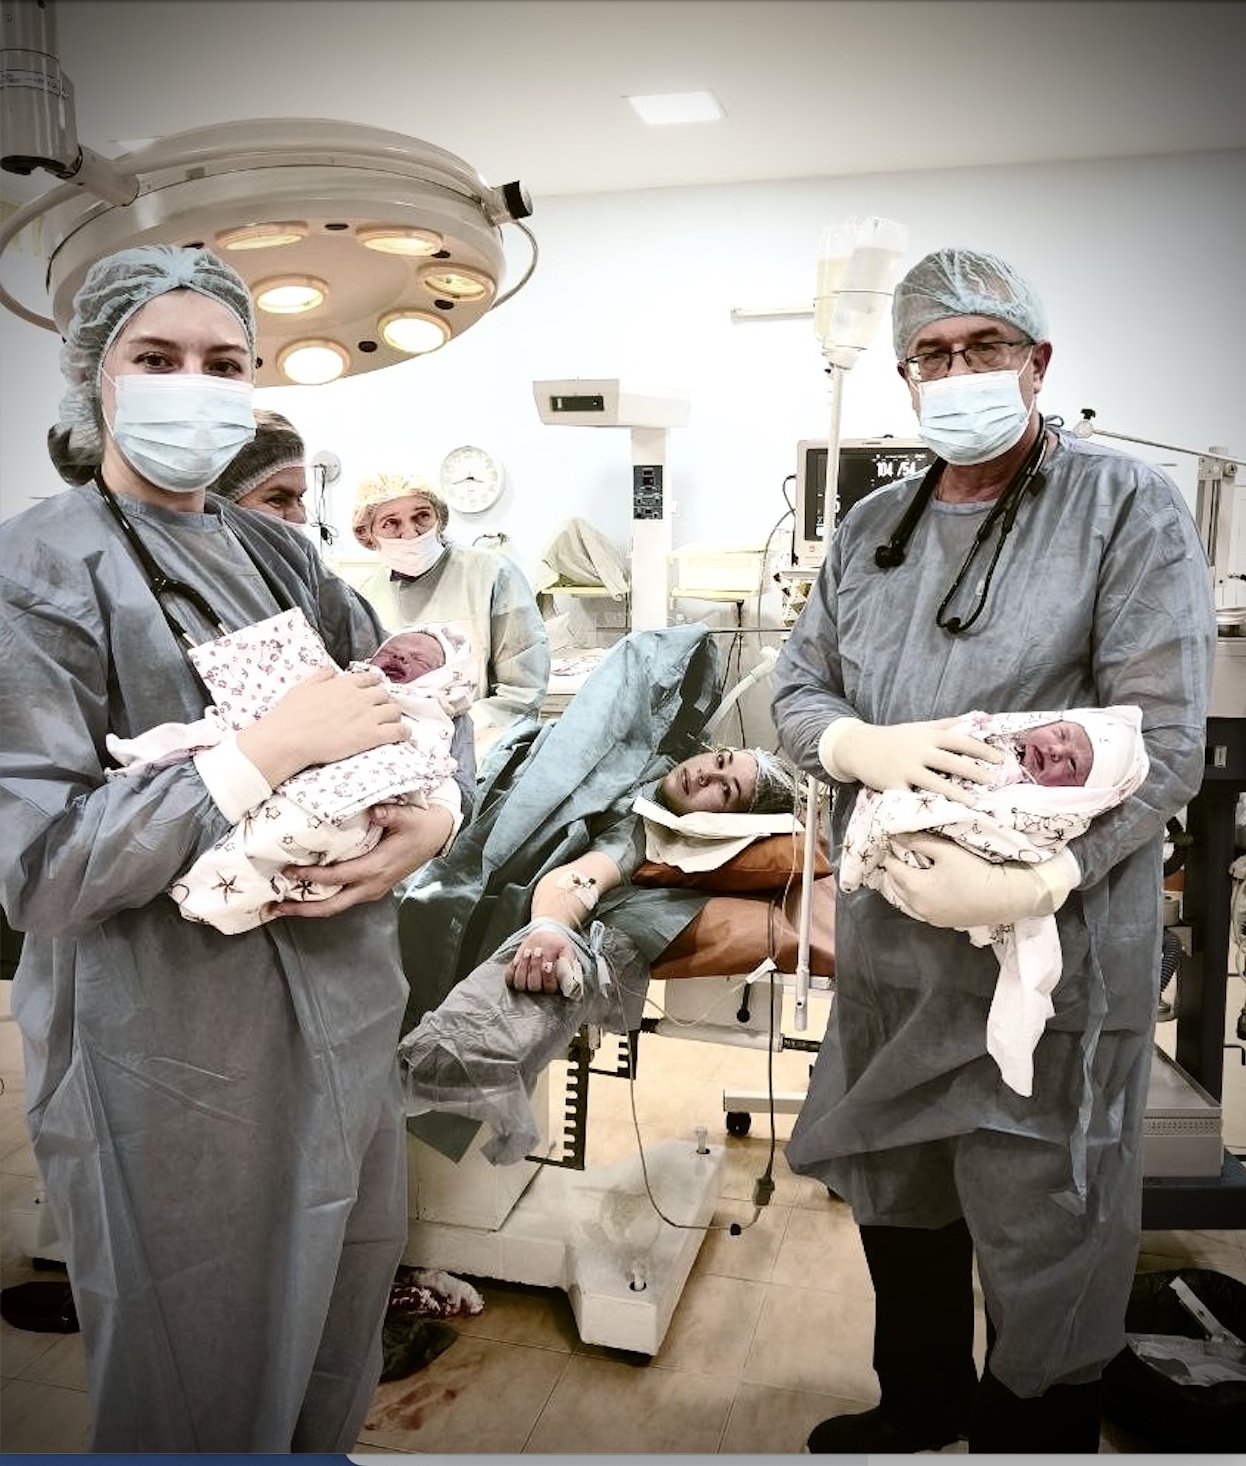
New equipment for the Neonatal Resuscitation Unit and the Neonatal medical staff of Dnipro Hospital which was damaged by Russian missles, now reopened in December 2024.
Chip Filson
I just discovered the movie Yes Virginia, There is a Santa Claus. the family drama based on a fictional story of the creation of this most reprinted of all newspaper editorials.
The New York Sun editorial, printed in 1897 by Francis Church, responds to a letter from an eight-year-old Virginia O’Hanlon asking if Santa Claus is real. The film presents social circumstances still present today—anger at immigrants., poverty and unemployment, the corruption of big money, women’s roles, and the sanitizing power of the press.
But the editorial’s message resonates still because it offers an understanding of belief and hope. After affirming Yes, There is a Santa Claus, the writer provides his logic:
Alas! How dreary would be the world if there were no Santa Claus! It would be as dreary as if there were no Virginias. There would be no childlike faith then, no poetry, no romance to make tolerable this existence. We should have no enjoyment, except in sense and sight. The eternal light with which childhood fills the world would be extinguished. . .
. . .there is a veil covering the unseen world which not even the strongest man . . . could tear apart. Only faith, fancy, poetry, love, romance, can push aside that curtain and view and picture the supernatural beauty and glory beyond. . .
No Santa Claus? Thank God he lives and he lives forever. A thousand years from now, maybe 10 times 10,000 years from now, he will continue to make glad the hearts of children.
The editorial captures the hope of this season. It is rooted in the lives and circumstances we all share. Hope “exists as certainly as love and generosity and devotion exist and give to our life its highest beauty and joy. “
It is these diverse presences, not presents, that bring forth this season of gratitude and love.
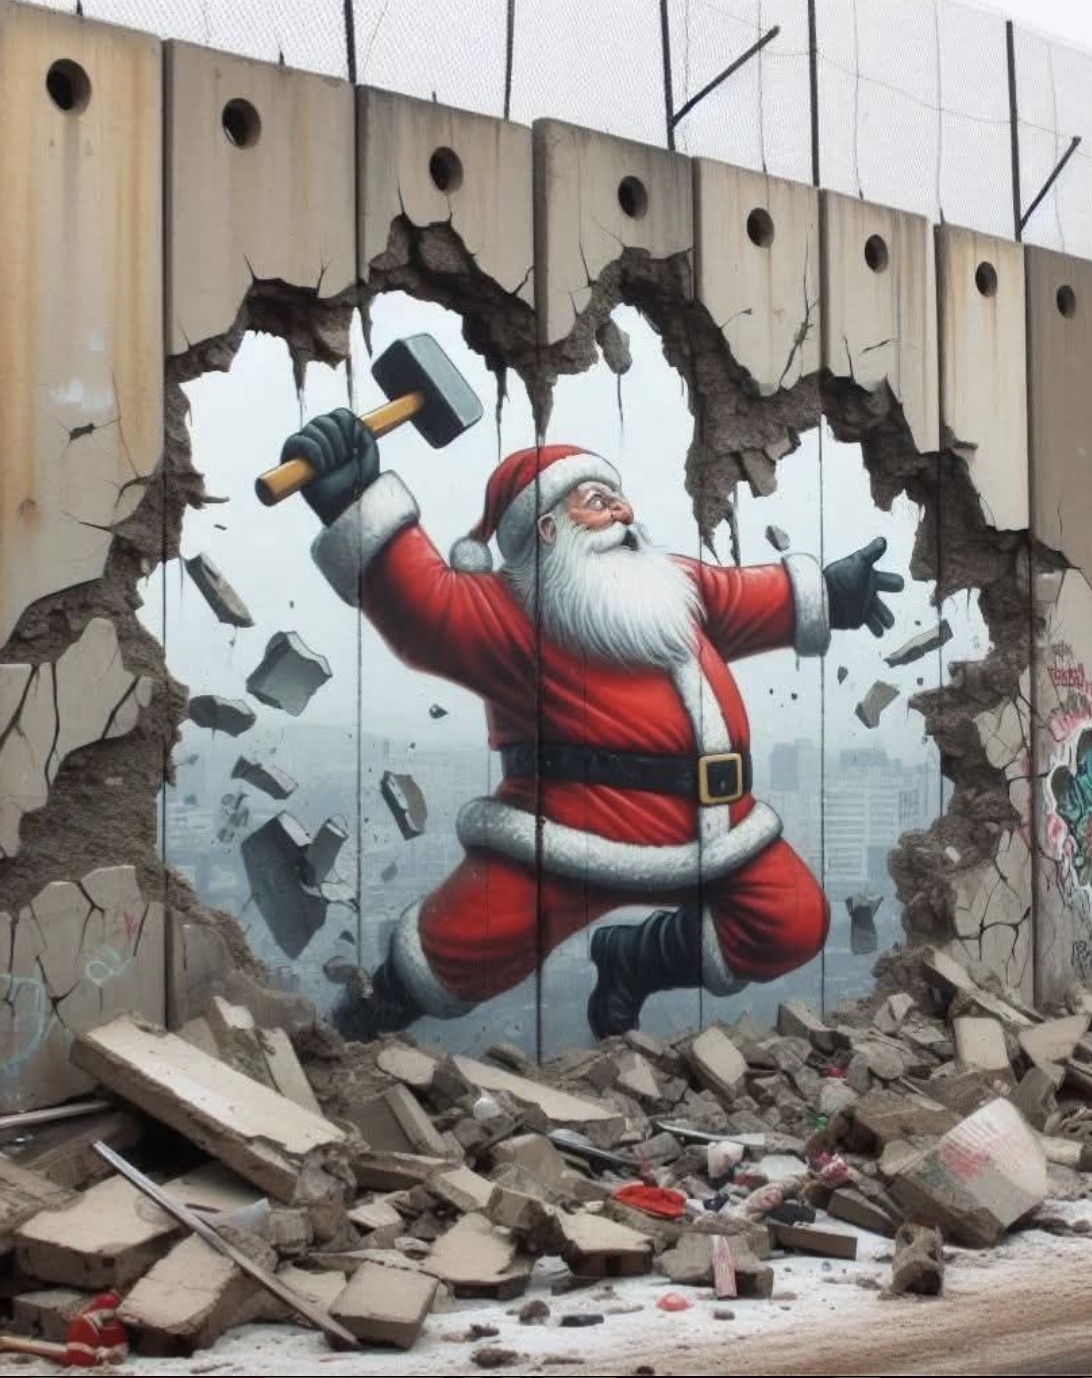
The World as it is: By English artist Banksy
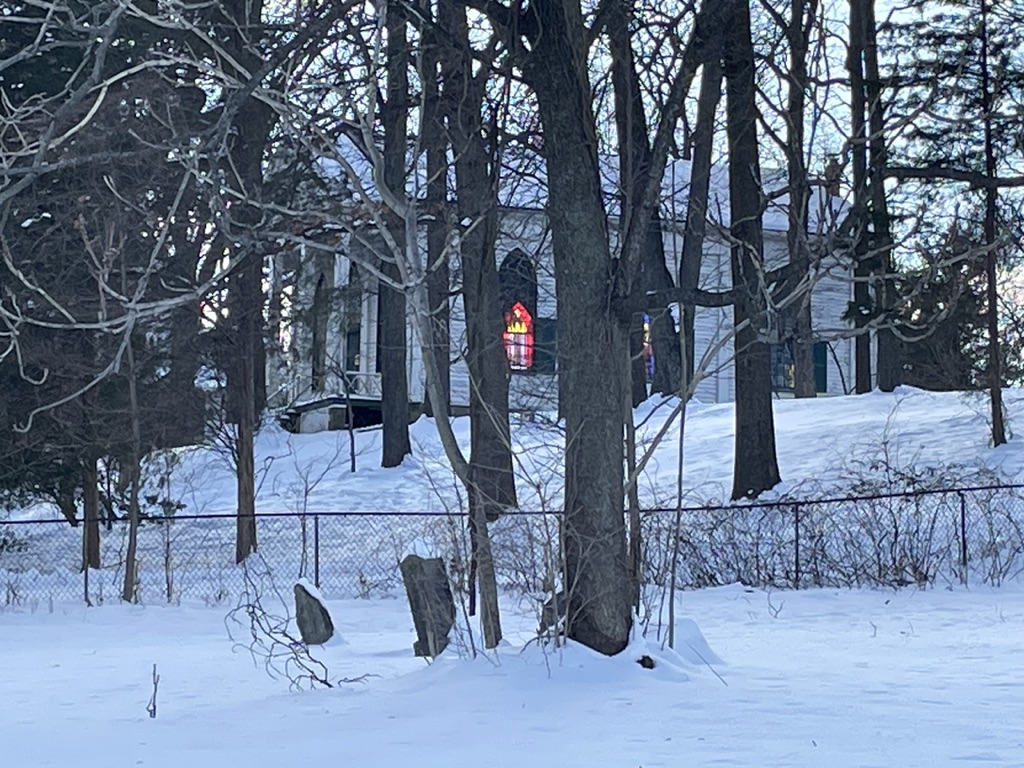
The World as we wish it to be: Bethesda Meeting House being reborn
In a beautifully composed family Christmas letter, the final paragraph is the closing stanza of a poem Walls and Bridges. It was written by the husband to his wife in celebration of their 53 years of marriage. The poem recounts his thoughts listening to a priest’s sermon in Hamilton, Montana during the peak of the 2024 election season.
You asked me why I go to church,
When so many that we know no longer do.
And I replied,
I don’t know where to find
A better explanation of the world
The way it is and the way
We want it to be.
The opening paragraphs of this December 11 article by Cinnamon Janzer of Next City:
In 2022, Etsy’s earnings topped $109 million in consolidated net income. “Despite significant macroeconomic headwinds, we maintained the vast majority of our pandemic gains and delivered double digit revenue growth and excellent profitability for the year,” Etsy CEO Josh Silverman said in a press release.
Days later, Silverman announced that the marketplace platform would raise the transaction fee Etsy takes from each sale from 5% to 6.5%. In response, some 14,000 Etsy sellers closed their shops and went on strike for eight days.
The article presents details of the initiative to build a better digital marketplace where members would own the platform.
The goal was to create an organization with a direct stake in the livelihood of its user artisans.
The Artisans Cooperative was launched in the fall of 2023.
The funding model is described on the website and includes both members and owners. Outside assistance from groups like Start a Coop, Operation Buffalo and Seed Commons was also important.
The effort is still a work in progress. No credit unions have apparently been involved yet. But it would seem a natural affiliation and potential further benefit of membership for the coops users.
The most important message is the artisan-organizer’s belief that people have the option to organize and manage their economic efforts with a cooperative design. Certainly a spirit much in need of rekindling in the much older and larger credit union system.
Read and ask if your credit union has this belief in its mission for its members.
Wednesday the Federal Reserve will announce its latest overnight Federal Funds target range. After it began its 2022 upward interest rate cycle to reduce inflation, the impact on share growth and credit union liquidity was significant.
Actual share growth in 2023 was just over 2%. This year the third quarter results indicate a n increase of only 3%. The long term average share growth since 2000 is 6.5%.
Whatever the Fed’s says about its future rate intentions. trends suggest that liquidity will continue to be a top priority for credit unions next year. This means slow share growth, longer term investments still underwater, and continued competition for consumer deposits from money market mutual funds and other consumer financial options.
One economic variable that all market participants debate is what will be the “neutral” rate of interest for the US economy once the inflation rate cycle tightening is ended.
The neutral setting is the range which doesn’t stimulate or slow economic growth. The market got used to very low Fed Funds interest rates during period following the 2008 financial crisis through the 2021 Covid response.
However these ultra low short term rates were contrary to the history of the Fed Fund level, and related market rates, prior to that post-crisis era.
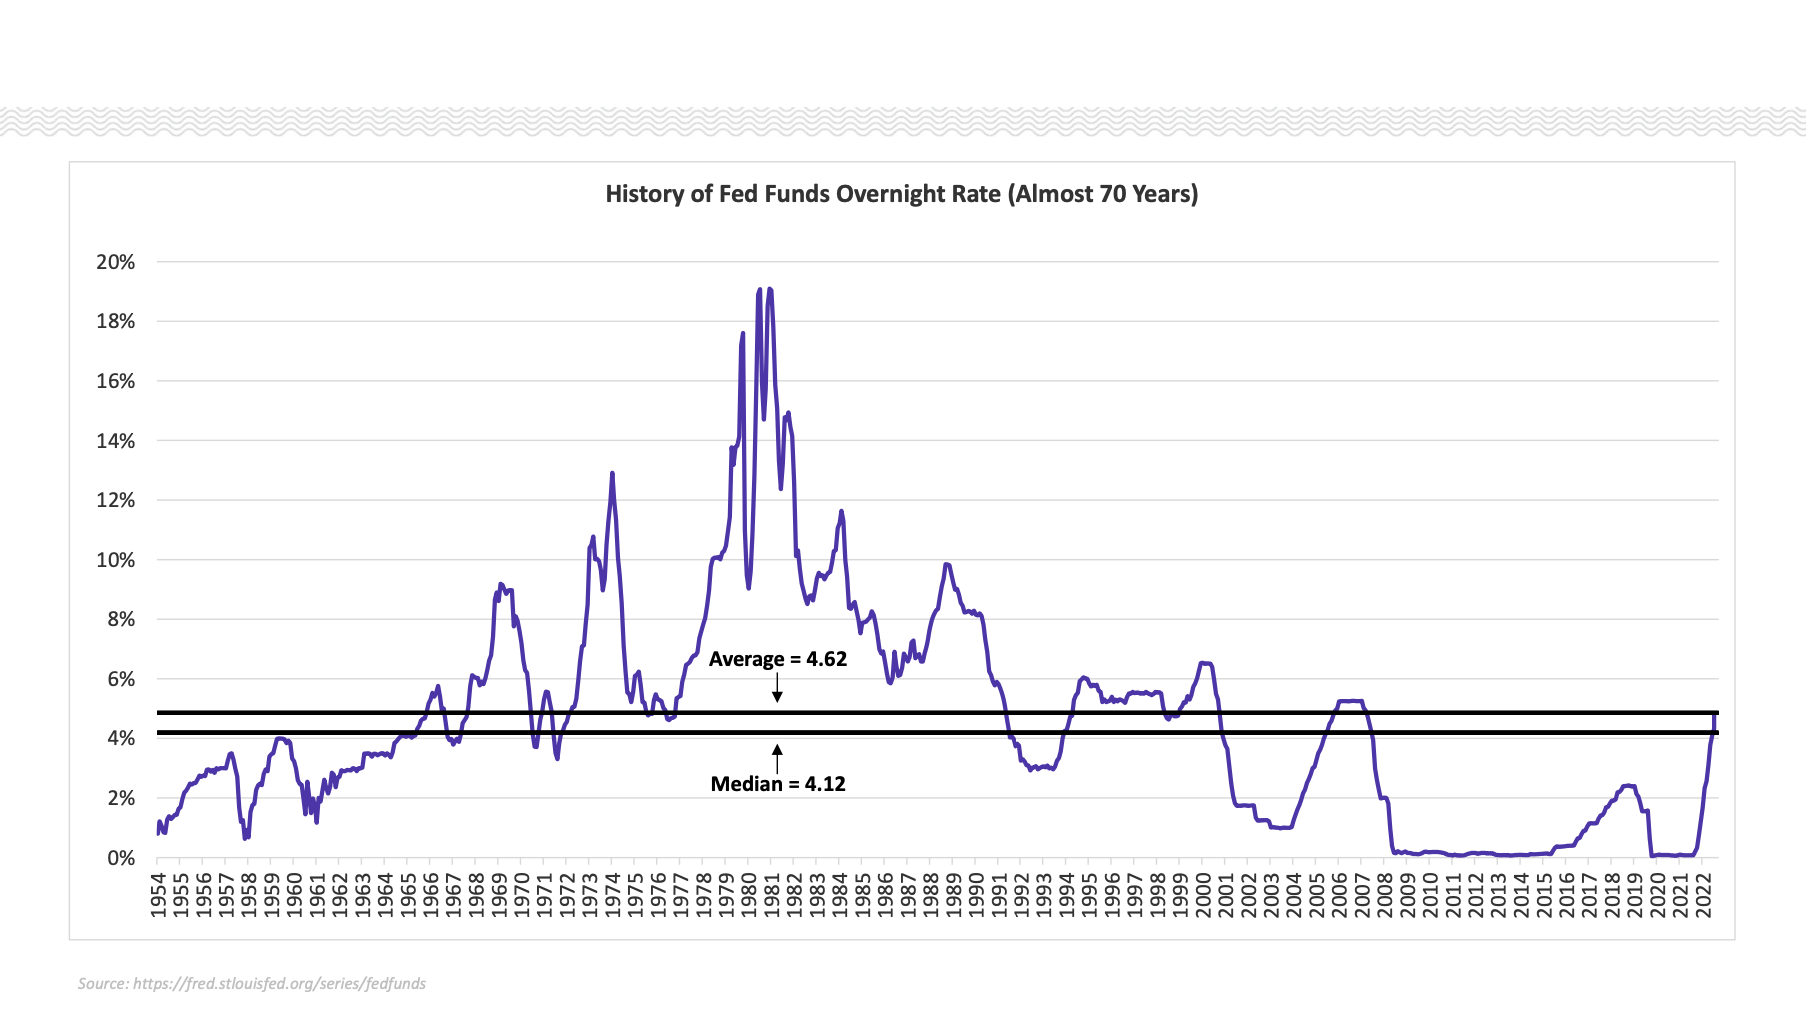
There is no consensus on what this “new” neutral rate might be. Bond traders’ and economists’ forecasts range from under 2% to the current 4% plus.
In this chart and comment below, Bloomberg’s December 15 Forecast shows the Federal Reserve governors wide divergence of outlook.
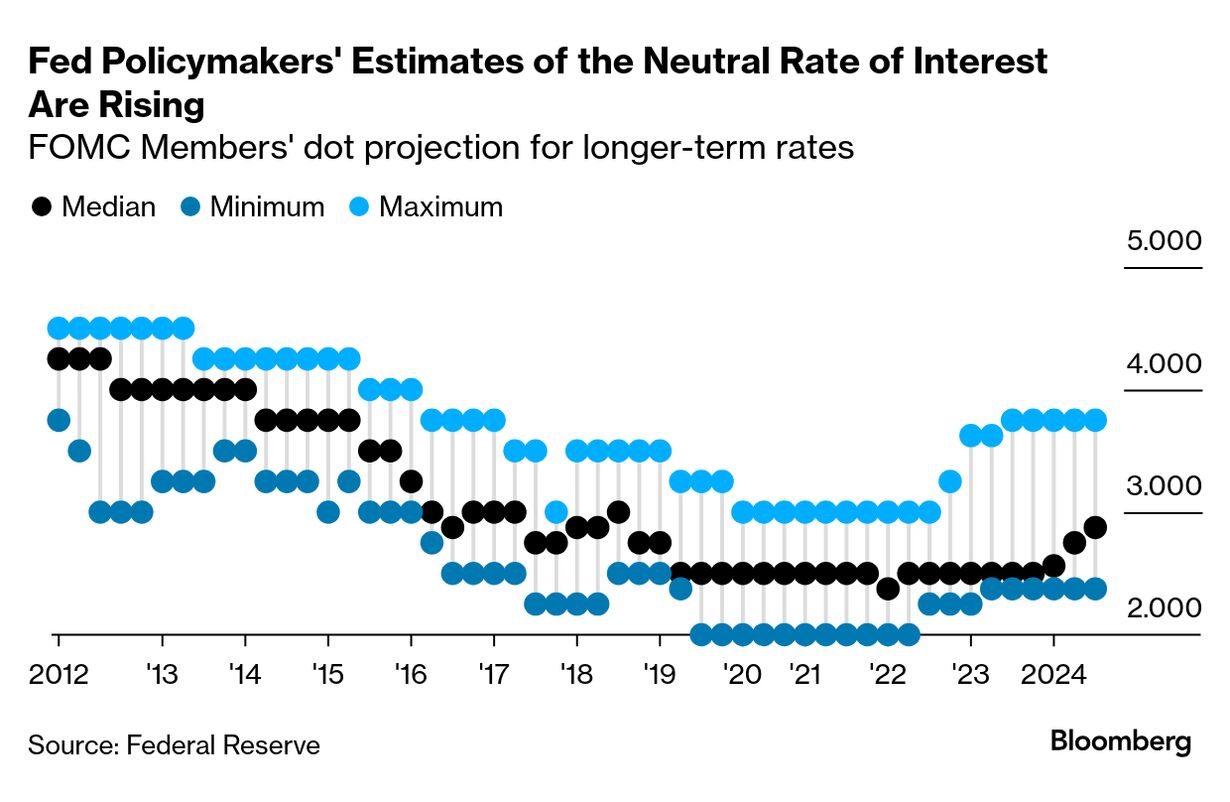
Fed policymakers’ estimates of the long-run interest rate — a proxy for the neutral rate — are divided, too. They’re as low as 2.375% and as high as 3.75% — the widest range since the Fed began publishing the figures over a decade ago. Next week FOMC members will update their estimates of the long-run rate. Keep an eye on whether the median estimate increases — and whether the range of opinion is narrowing or expanding. (Bloomberg)
Credit union funding is almost all from short term savings. A flat or inverted yield curve if the FF rate stays above 3% can squeeze the net interest margin and/or make growing deposits very difficult.
A second unknown is how the growing interest payments on federal budget will affect rates. Could government financing “crowd out” private market debt, that is make it more expensive for corporations to borrow versus relying on internally generated cash flows?
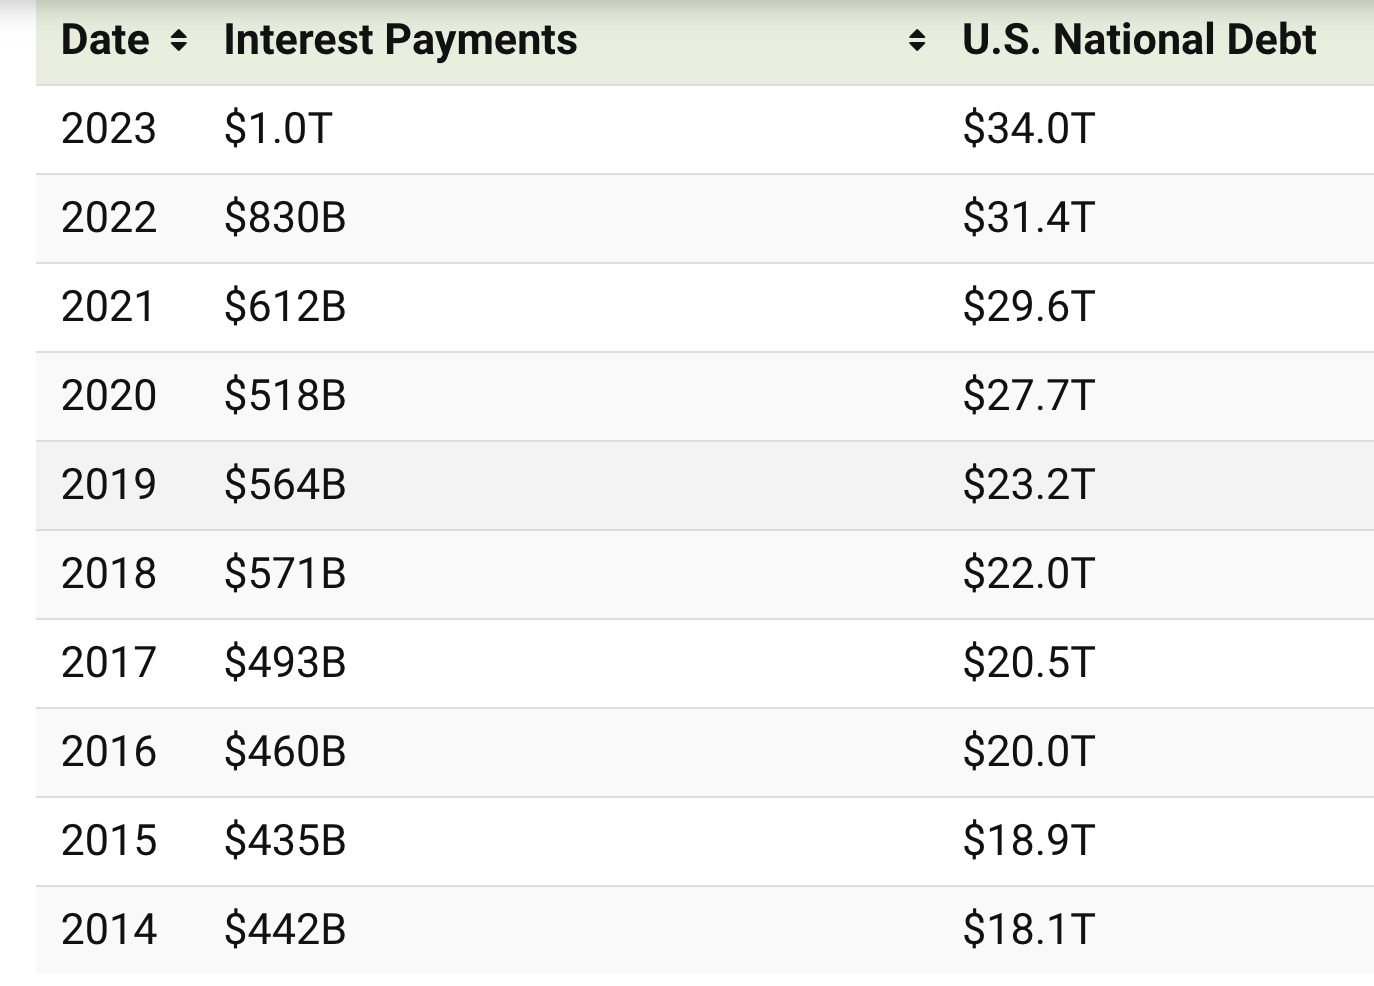
With other aspects of the new administration’s fiscal policy uncertain–taxation, spending, tariffs, etc–the rate environment going forward looks anything but certain.
Credit unions which rely on external new member share gowth versus relationship share strategies, may find it necessary to continue to pay up to attract these funds.
The Fed’s rate announcement this week will be well reported. The difficulty will be interpreting any future direction from it.
No one knows what’s next for market rates and forecasts. However, liquidity and slower growth are likely to be an ongoing challenge for the cooperative system in 2025.
This post presents ways the spirit of the season is incorporated in commerce. Some of the most memorable ads are by the John Lewis stores in England. In recent years they have become more unique and less nostalgic in their storytelling approach.
Here is an example from 2023:
(https://www.youtube.com/watch?v=Cyuqy4Eb_I4)
Sainsbury’s approach to selling food for the holidays.
(https://www.youtube.com/watch?v=I8dczAGg-Qg)
AShelter’s Christmas campaign, is a poignant film that sheds light on the harsh realities of homelessness affecting over 150,000 children in England. The story follows a young girl named Mia and her father as they journey through a whimsical, imagined world – a temporary escape from their grim living situation in temporary accommodation.
(https://www.youtube.com/watch?v=PNZd-O-O_6s)
This Christmas story from Germany ends with a family tradition familiar to all.
This video is a moment when the spirit of the season stops all shopping in a large Philadelphia Department store.
(https://www.youtube.com/watch?v=wp_RHnQ-jgU)
Which exresses the spirit of this season for you?
Biennially, the FDIC conducts a consumer banking survey and releases the results to the public. The report produced since 2009 traditionally measures the unbanked portion of the population. The 2023 data released on November 12 added several questions about two new financial services that have attracted much credit union interest.
The Report’s headline finding is that “96 Percent of U.S. households had credit union or bank checking accounts in 2023.” A record low 5.6 million households (4.2%) remain unbanked
Further data breaks down the unbanked by race and those that were “underbanked,” 14.2% of households. These consumers rely instead on payday loans, cash and other non-bank products.
For traditional relationships, 48.3% of banked households use mobile banking and 76.4% of all households had a credit card.
Between the surveys in 2021 and 2023, the data on new payment application shows “use of nonbank online payment services such as PayPal, Venmo, or Cash App increased, while the use of general-purpose reloadable prepaid cards decreased.”
So much for traditional product tracking. The 2023 survey asked about household use of two newer financial services: Buy Now Pay Later (BNPL) usage and crypto purchases. Both products have raised much interest in credit union land.
For example, this December 2 article in Credit Union Times reports on the first credit union in Georgia to offer a BNPL product. The article quotes the credit unions fintech/CUSO partner providing the service: “Buy Now, Pay Later is a financial service that consumers want and are increasingly expecting from their primary financial institutions.”
The FDIC survey however reports that “only 3.9% of all households used BNPL in the past 12 months.” For many consumers, this option is just an extension of an existing credit card relationship, not a separate product.
As bitcoin passes $100,000 in value and then fell back, crypto is again on some consumers financial product short list. But how big is the market?
The FDIC data showed that “In 2023, 4.8 percent of U.S. households owned or used crypto or digital assets in the previous 12 months. A significant majority of these households held crypto or digital assets as an investment (92.6 percent) while only 4.4 percent of these households used digital assets as a form of payment.”
Again the urgency to offer purchases or other transactions involving bitcoin or other crypto “currency” would seem to be tempered by both the uncertain nature of the product and its relatively low penetration of households.
The good news is that traditional financial products are used by almost all households and mobile convenience continues to expand.