Buffett’s Wisdom For Credit Unions: The Casino in the Cathedral

On Saturday CEO Warren Buffett’s four-hour, open-ended Q&A with Berkshire shareholders was a lesson in leadership.  In life’s wisdom. And in human values.   It was his last time as CEO.

If you read one of many excerpts or listen to a recording, you will be rewarded with a superb public discourse.

One observation is especially relevant to an issue confronting today’s credit union system leaders. That is the radically different approaches to assure future cooperative resilience.

The Casino within the Cathedral

Buffett stated in one response:  “Capitalism in the United States has succeeded like nothing you’ve ever seen, but it has what it is, a combination of this magnificent cathedral, which is produced on the economy like nothing… the world’s ever seen. And then it’s got this massive casino attached.”

The casino describes the speculative, short-term, and potentially risky side of capitalism, where quick gains and money changing hands are the primary focus. The allure and rapid growth of the “casino” can lead to the neglect or overshadowing of the “cathedral.”

Responding to a question about hedge funds entering the insurance business, Buffett pointed out that these firms, which specialize in buying and selling businesses, follow different “fiduciary  feelings” than Berkshire.  Berkshire’s goal is to acquire a business for the long term (forever), not turn around and resell for short term gain.  He believes his approach is the best way to create long term value for his owners whom he wants to retain as well.

The Credit Union Analogy

Today there are two broad business approaches followed by credit union CEO’s. Driving these are two different “fiduciary feelings” about where one’s duty is directed.

On the one hand are those who believe the CEO’s primary goal is to maximize institutional growth quickly.  In some instances, this is through mergers or purchasing external assets or even whole firms (banks).

The primary motivation is maximizing the rewards of leadership.  Sometimes this is while employed; or if not then, cashing out by handing the firm over to another credit union for the right personal compensation from a merger.

A growing current example is the increase in “mega-mergers.”  These multi-billion combinations offer the owners nothing that the individual firms cannot deliver.  Sometimes they are an effort to eliminate a local competitor; in others, it is to gain a larger space and personal reward in the credit union Cathedral.

This Casino approach to leadership is described by writer David Simon in the composition Privilege.  It ends with the words, I’ll play by  those rules:

It’s almost like a casino

You’re looking at the guy winning

You’re looking at the guy who pulled the lever

And all the bells go off

And all the coins are coming

Out of the one-armed bandit

And you’re thinking that could be me.

I’ll play by those rules.

A Composition for the “Cathedral”

The purpose which built the credit union Cathedral is captured in this 1850’s folk song by Stephen Foster,  Hard Times Come Again No More.

The first verse sets the scene:

Let us pause in life’s pleasures and count its many tears
While we all sup sorrow with the poor:
There’s a song that will linger forever in our ears;
Oh! Hard Times, come again no more.

Followed immediately by the rending chorus:

Tis the song the sigh of the weary; Hard Times, Hard Times, come again no more; Many days you have lingered around my cabin door, Oh! Hard Times, come again no more.

“It’s a song about poverty–financial poverty first and foremost, but it also hints at a poverty of spirit, of general misery.

“What’s refreshing about it, what makes it stick in our craw, is its honesty. It doesn’t flinch or pull back from showing real human suffering, bringing it to the very entrance to the drawing room: “Let us pause in life’s pleasures.”  (Source)

This 2010 recording is one of numerous current arrangements.  It uses pictures of the Depression to reinforce this 170-year old challenge for the American economy.  It could be a National Anthem for the credit union movement.

This second arrangement is how a credit union leader like  Doug Fecher (former CEO of Wright-Patt CU) might have recorded with his group when presenting his vision.

How credit union CEO’s make this business choice  will determine whether the movement can maintain its Cathedral.  Or become just another group playing in the casinos of capitalism.
 

An Annual Meeting that Owners Stand in LIne to Attend

Would your members take time to attend your annual meeting?  Is it an occasion the owners look forward to?  Will they learn something new?  Have a chance to meet board and senior staff?  What would the local newspaper or the credit union press write about the event?

Every  credit union that has issued news releases or been in the press this past year knows the value of public coverage.  The annual meeting is an opportunity to celebrate results, profile the leadership and show respect for the owners who make it all happen.

The “Woodstock for Capitalists”

This weekend in Omaha, NE Warren Buffet will lead Berkshire’s annual meeting.  It is a multi-day event for shareholders who travel from across the country and even foreign countries to attend. The excitement and preparations are described in the WSJ article from April 29.  The company has sent tickets to over 138,000 shareholders and another 6,000 to non-owners who want to attend the event and pay $5.

The actual meeting is so popular that CNBC will broadcast the event live-in Mandarin and English.  The high point will be the initial open-ended Q&A with Buffet and deputies answering questions from viewers and attendees—for hours on end.

This public dialogue always makes headlines as the annual report has been released months earlier.  Not just owners, but the general public is interestedd in Buffett’s observations on tariff’s impact, economic uncertainty, the role of America in the world. Viewers will want to know what the company might have in mind with its $350 billion in cash.

Buffett’s annual conclave for individual owners is a long standing show of respect to those millions of small shareholders versus the billions owned by investment companies such as Vanguard or Fidelity.  He rewards their loyalty by being with them, talking openly and sharing his leadership approach including succession.

The spirit is that “we are all in this together” and “I work for you.”  His approach is an example of a leader accountable to owners and creating a community of shared purpose.

A Buffet without Buffett

What credit union wouldn’t want this same spirited outcome?  But few even try even though the cooperative model presumes this same common interest among member-owners.

One credit union that has attempted to create is own sense of shared accomplishment and celebration is the $160 million Affinity CU in Omaha, NE.

At the annual meeting I attended two years ago there were talks by the state regulator, the President of the Iowa Foodbank as well as the required  CEO and Chair reports.  Scholarship winners were recognized, there was a free buffet dinner for entire families, prize giveaways and even video of one of the members telling his story.

The meeting included the election.  After which all board members, new and old, took their oath of office, in front of the owners.

This was an occasion combining all the elements that make Berkshire’s effort a national news event. It is not an organization’s size and resources that creates owner excitement for this required  meeting.  Rather it is the measure of leadership’s respect for the owners for whom they work.

An Annual Meeting Experience

The formal invitation came by mail and read as follows:

TowneBank

Cordially invites you to attend the:

Annual Meeting of Shareholders

Wednesday May 14, 2025  at 9:30 AM

The address for the meeting was the Richmond Convention Center. The invite closed:

Lunch will be served immediately after the meeting

Kindly reply by returning the enclosed card only if you plan to attend

The reply card asked if the attendees would stay for the luncheon.   The only required information was first and last name of those attending.  There was an addressed stamped envelope to mail the response.

TowneBank is $17 billion in assets with  2,800 employees in 51 branches throughout the greater Richmond, VA area.   TowneBank  converted from a mutual charter several decades earlier.  In that process depositors could buy  newly issued shares if interested.   My wife converted her  savings to stock.

TowneBank’s mission is:

Serving Our Community

Throughout our growth, we’ve never lost sight of our true mission: to continue to be a community asset by serving others and enriching lives.

Respect for the Owners

As a shareholder-owned financial institution, their board’s  goal is to provide its owners an acceptable return and ensure trust and confidence in the firm’s leadership.   Its invitation is gracious, formal in style and intended to encourage owner participation.  It feels welcoming.

A Credit Union’s Annual Meeting

The annual meeting of many credit unions conveys just the opposite impression.  Member-owners must register in advance to attend the meeting.  The event is often virtual only, with no member attendance permitted. The agenda may state as mine did: 

Matters requiring a vote

Please note that there is no new business to discuss. The only matter requiring a vote of the members in attendance is approval of the 2024 Annual Meeting minutes.

There is no voting for directors as the board nominated candidates equal the vacancies. No new items or old business will be permitted. There will be a Q & A for questions submitted in advance, and sometimes those added during the meeting.

This was the setup for Patelco’s 2025 virtual annual meeting last Friday.  There was much material a member-owner might download at this site.   The State of the Credit Union included 46 slides with much information both financial and operational efforts. The 2024 Annual Report is 18 pages of high level summaries, a financial statement (unaudited) and pictures of staff and board.

Patelco’s annual report and CEO meeting update met the letter of the law, but the Friday event lacked any hint of spirit. No celebration, no thank yous to members and carefully scripted to create an impression of a required exercise versus a shared experience with member-owners.

The Q&A Portion

The only section not prepared and sent in advance were member questions. Some were submitted prior and some during the meeting.

The cyber ransom attack was a major disruption in 2024.  It was discussed in the CEO’s summary and in the Q & A.  New information included an estimated total cost of $64 million of which  $37 million was fraud losses caused by some 6,000  members during the outage.  Their accounts were subsequently closed.  The sale of Visa shares in January resulted in a $35 million gain which helped offset part of the cyber attack expense.

The Annual Meeting’s Intent

Is the Annual meeting a mere administrative formality to be closely controlled by the organizers?  Or, is it an opportunity to enhance member confidence and support for their cooperative?

The meeting ritual can be much more than publishing required data and information. It  communicates leadership’s attitude toward their member-owners. Patelco’s approach signals control not mutual responsibility.  There were two examples that illustrate this approach.

Democratic Governance

When asked about the closed election process Chairman Rivera read the formal steps. He said there were no limits to board terms. Two board members’ service began in 1996. As of the next meeting, five more will have served for over two decades. Longevity is certainly an attraction for those in power.

The Chairman carefully avoided addressing the issue of democratic governance for topics such as: When was the last meeting in which there was a contested vote?  Ever? Why does the board encourage members submit proxies, thus surrendering their right to vote in board elections?  Why are no members allowed to attend in person?  How meaningful is the member’s meeting  in which all business is conducted with only employees present?

At a time when every segment of the country’s democratic processes seem to be under direct or implied threat, why is Patelco shutting down the democratic practice meant to be the hallmark of cooperative design?

This was a missed opportunity to highlight  fundamental cooperative governance.

Questions About Threats from Without

The second reason for engaging members is that this is the source of the movement’s political power.  Credit unions cannot out spend political funds or have enough lobbyists to rely on traditional forms of political influence. It is members voting their self interest that will secure credit union success in DC.

Three questions touched on  national topics. One was whether Patelco was safe and sound at this moment, referring to bank problems. A second asked about possible threats from a government agency. The CEO’s response interpreted the question as referring to credit unions’ tax exemption.

And the last question of the evening: After President Trump fired two of the three NCUA board members—does this threaten our deposit insurance?  CEO’s answer paraphrased: Your deposit insurance is not threatened, the NCUA board is reduced from three to one member but can continue to take the actions it needs to;  your insurance is federally backed. 

These questions referencing the external environment (taxation, NCUA board firings, bank uncertainties) were an opportunity to educate and prepare members for their critical role in countering these threats.  It was the moment to rally the members with straight talk.  Instead general assurances that everything is OK were given.

To suggest taxation is a just another banker’s campaign is to overlook the entire current context.  True as always, but that is not what is going on that makes this a potential opening now. The response that the firing of two NCUA board members means “business as usual” at NCUA and the NCUSIF, is ill informed or naïve.

Both questions were an opportunity to remind members about credit union uniqueness and why there is a federal tax exemption—the purpose and role of cooperatives in a capitalistic market place.   More vital, this purpose is regulated by a unique dual chartering framework. That system includes insurance fund options that require 1 cent of every member’s savings dollar be sent to capitalize their special cooperative fund.

To blithely assure members their fund and NCUA  function like “business as usual” is to misstate the whole intent behind the board’s two removals.  Moreover, the question of NCUA’s single member board authority is anything but settled.

If this is indeed the view of Patelco’s leadership about DC events, they need to do some homework.  More importantly, their power to address these topics will rely on member awareness and the ability to rally their engagement when needed.

The Bottom Line

Credit unions are different by design until those who lead them cease to believe in that difference.

TowneBank believes in courting and encouraging shareholder engagement. They talk the same language as credit unions about community and customer support.  But they back that community spirit up with invitations and hospitality.

Patelco’s actions speak much louder than the many pages of charts, numbers and operational activity in prepared reports. The annual meeting is not a member’s final exam for the prior year. It should be a celebration of mutual progress.

There has never been a time when acting to support democratic values and practice has been more vital.  Credit unions should be leaders in this affirmation of member-ownership and governance.  Without this effort, credit unions will increasingly be perceived as just another example of self-perpetuating oligarchy at work.

“Take Action Now”

That was the request of O Bee Credit Union President Andrew Downin’s recent letter to his members.

Dated April 18, two days after the Trump administration fired the two democratic board members at NCUA, I thought this was fast action.

The immediacy of the situation was different however:

We need your help. 

A proposed change in Olympia (WA) could directly impact O Bee Credit Union and the services we provide to you and our community. A last-minute amendment was added to Senate Bill 5794 that would impose a new tax on not-for-profit, Member-owned credit unions like O Bee. This amendment was introduced without any public input and ignores the real value credit unions provide. 

This new tax would reduce our ability to offer affordable loans, low fees, and financial support to our Members. It’s not just a tax on O Bee – it’s a tax on you, our Member-owners.

The email closes with this request:

TAKE ACTION NOW*
* This link takes you to a trusted website from our partners at GoWest Credit Union Association.

The letter ends with: Thank you for being a part of O Bee Credit Union. Together, let’s stand up for what makes credit unions special.

What Makes Credit Unions Special?

In this event, the credit union threat is from a change in the state’s tax exempt status. There is direct parallel at the federal level.

But threats to credit unions are more than taxation. Last week the Trump administration took over NCUA.  With a single board member whose term expires in four months, the agency will either bow to Caesar or navigate to keep member-owners’ interest first.

If the latter course is followed, it will need the support and engagement of the members. This existential threat may be harder to rally for member action versus opposing taxation,  No one is for taxes.

But it is critical to point out the NCUSIF logo on the credit union’s marketing materials represents a uniquely credit union designed and dedicated cooperative fund.  Even this email includes the words:  Federally Insured by NCUA.

During the Silver State banking crisis in 2023, the credit union community promoted their separate insurance fund as well as the differences in institutional structure and risk versus banks.

Many factors make credit unions special.   For me the most important takeaway from this communication is not the issue of a tax change or  the current Agency takeover in DC, but rather the request for members to act.

It is member involvement that will separate the credit union issues from the transactional lobbying circus in Washington.   O Bee does an excellent job communicating their credit union’s uniqueness in their monthly messages.

This corporate discipline to stay connected with members is a potent power.  This was the first but not the last time members will be asked to take action in the months ahead.


Our Moral Moments

When Jim Blaine was CEO of SECU(NC) he was sceptical of his peer’s elaborate strategic plans.   Instead he offered his mimalist version as follows:

Vision:  Send us your Moma.

Mission: Do the right thing.

These were guiding principles for how to serve members as well as evaluate tactical business options.

I was reminded of this simple guidance when reading the following “bettter deal” story from a CEO’s update for the staff and board:

Another member, Jessie, was set on purchasing a vehicle from Carvana for $19,880, even though its actual value was $15,300. While he was still willing to proceed, I wanted to ensure he got the best deal.

After a quick search, I found the same vehicle, in the same color and trim, but two years newer at a local franchise dealer for the same price. The vehicle was priced at its actual value, making it a far better investment. Jessie ended up purchasing the newer vehicle and closing through CUDL, securing a much smarter deal.

These are Not Normal Times

Yesterday another administration error was corrected by the Supreme Court which ordered that a migrant mistakenly sent to El Salvador be returned to the US.  The administration denied it had the power to do so.

Senator Cory Booker recently spoke:

“These are not normal times in America, and they should not be treated as such. This is our moral moment. This is when the most precious ideas of our country are being tested….”

As DOGE has now moved into NCUA, it is important to remember Booker’s assertion that,  “In this democracy the power of people is greater than the people in power.”

The Wrong Part

While resignations on principle, the dismissal of career federal employess and wholesale demolition of federal government departments may  seem remote or even necessary to some, the continued destruction of government services will ultimately negatively affect every American.

But we need look no further than credit unions to see how hard it is to follow Jim Blaine’s simple maxim to do the right thing.

CUDaily founder Frank Diekmann recently wrote an opinion piece Lots of Questions About Mergers. He .summarizing the multiple motives given members including examples of questionable accuracy:

The vague claims about “more products and services” and “better rates.” The big payouts for some management teams and nothing for the members. Whopping amounts of net worth just being transferred to the acquiring CU. And relatedly, a question that is never answered: if you’re lamenting you just couldn’t offer certain products and services, why didn’t you tap into some of your deep pile of capital? 

Also related, and a question I wish I could ask of many CUs: where in the world has the board been over the last few years or decade?

Our Moral Moments

What we are seeing in our public and professional lives show the inevitable challenge every person encounters at some point.  Perhaps more than once as we grow through stages of increased responsibility and accountability.

We all believe in our hearts we will do the right thing when necessary.  Unfortunately many others rely on a reality that “everyone has a price” with which they can be induced to go along.

Author and spiritual leader Richard Rohr described this human circumstance as follows:

It may not be in our power to determine how things will unfold, but it is in our power to decide how we respond. It is in our power to hold on to the practices that nourish us, inform us, and give us courage. It is in our power to remain in integrity, to choose nonviolence and noncooperation in the face of all the wrongs we are seeing. 

The beginning of a way out is to honestly see what we are doing. The price we’ll pay is that we will no longer comfortably fit in the dominant group!

Doing the Right Thing may not put you in the dominant group.  Remember that your ability to resist is because others gave you the personal wherewithal to both see and chose another way forward.  That is the individual foundation which all institutions require to survive.   We call that personal responsibility democracy.  It is how we achieved the freedom we share today.


With Whom Do You Share Your Brand?

One of the truisms about branding is that grreat companies create great brands.  Brands do not build great companies.

Tim Calkins is a markeing professor at The Kellogg School of Northwestern University.  He publishes a monthly newsletter, Strong Brands,  providing contemporary  examples from his classroom.

The latest edition includes an update on Tesla, a brand he has written about before.

Tesla
In my last post I wrote about Tesla’s brand repositioning. Things seem to only be getting worse and sales were sharply down in the first quarter. News that the Proud Boys are now showing up at Tesla dealers to show their support will only further polarize the brand.

Driving a Tesla has always been about making a statement. I suspect supporting the Proud Boys wasn’t the statement most Tesla buyers were trying to make. 

Credit unions have both individual identities as well as the generic reputation of being a different kind of financial institution.   What one credit union does well or becomes a front page story,  affects the cooperative system’s brand.

Just as important the individuals and organizations a credit union decides to work with or to support affects their reputation with their members and the communities they serve.

As credit unions decide their NIL relationships, the business partners they seek to serve, and the community events they support, they are creating a reputation much greater than a financial service option.

As boards consider whether to facilitate digital currency options, the sale of marijuana or vape products, or finance options such as interval vacation  ownership, consider the impact on the “brand” the credit union is presenting  members.

When a credit union offers  a special financial product or specific business loans, it endorses that activity.

For example is now the moment to promote a special financing option for the purchase of Teslas?

As in life, what credit unions do with members; money always speak louder than the latest PR or messaging  campaign.


It’s the Members Who Have the Power to Bring Change

Uncertainty reigns in Washington DC about the future of federal government agencies and their traditional roles versus the public.

CDFI grants are threatened; minority (democratic) board members of the FTC are fired; agency personnel are asked to submit weekly updates to DOGE on their work. Credit union taxation is on some agendas. NCUA board members spar over OD fees, versus uniting to support the agency’s mission to serve credit unions.

As the political and constitutional events evolve, the outcome will depend on political power.  For credit unions, this is the voting and lobbying efforts of their members.  Every industry “walks the hill.”  Every paid lobbying group makes PAC donations.

But few groups would claim the potential clout of member-owners acting to protect their democratic institutions.

All Politics Is Local

Despite the news from Washington, all voting is done locally.

However, this member constituent power is latent.  Asking for action requires informed  awakening and clear messaging.

An immediate way to activate this process is to engage the members at the annual meeting.  That is where their attention as owners and their role in governance is exercised.

The required annual baord election is the opportunity to affirm their potential political role by making this a real meeting, not a pro forma event.  It starts, as shown in the example below, by showing how their board members are nominated and then voted on as part of the meeting.

The Chair and CEO’s reports should illustrate  their credit union’s special role in members’ lives and in their communities.  When presenting threats to the cooperative model, the members will know what is at stake.  Finally, specific actions they may be called upon to  support their  member-owned financial cooperatives  should be discussed and feedback sought.

Activating Member Empowerment at the Annual Meeting

Here is the lead story in the March 13, 2025 email to members by O BEE credit union.

Transparency and Trust

The link at the end of the article lists the duties of the board, includes an application to be a nominee, and details of the board’s compensation.

Transparency is vital to a credible election process.  This strengthens  members’ awareness of their governance role. When the credit union then asks them to a act as citizens in a democracy, you have already “walked the talk.”  They can trust that you have their best interets in mind.


Videos Empowering Members and their Credit Union

Putting members at the center of a credit union’s story is an art.  When done well, it reinforces the fundamental cooperative difference, especially when an integral part of the public message.

One credit union that does this with great skill  is Whitefish Credit Union in Whitefish, MT.

“God’s Country”

Below is a recent example of their unique video series.  These member centered short films portray individuals’ special interests, the natural landscape of the area, and a broad community purpose being served.

Following is a story by a founder of the Back Country Horsemen on this non-profit’s 50th anniversary.  Their example has extended across the country.  As one person remarks, every state has its own “back country,” even Delaware.

The video makes you want to saddle up and be a part of this ride with this credit union.

(https://www.youtube.com/watch?v=wodQNsu5fSQ)

2025: The  Most Important Annual Meeting Your Credit May Ever Hold

Bylaws require every credit union to hold an annual meeting.  The agenda includes reports by the Chair, CEO, other timely updates and the election of directors for open seats on the board.

In many credit unions this event is purely administrative and perfunctory. It is merely a compliance task, carefully managed to end quickly, and to avoid any real member dialogue.

Such an approach this year could be the most costly political mistake a credit union could make with its members. Here’s why:

The future of the federal regulatory system is being overhauled for greater efficiency,  simpler design and more direct White House control.  No more  independent agency policy making.  One example of a question being raised is whether the  government should have two separate deposit insurance funds.

Influencing Political Outcomes

Credit unions, like most industries, have deployed traditional lobbying capabilities to counter political risks to their operations. These common tactics include raising more PAC dollars, hiring lobbyists with ties to those in office, funding PR campaigns, etc.

Credit unions will never outspend or out-hire their opponents.  Money is not the source of their political influence in DC or in their respective states.

Consultant and former OCC examiner Ancin Cooley offers this assessment:

In reflecting on the history of the credit union movement, one fact stands out: our strength has always been rooted in our members and communities. . .While political wins and advocacy play a role, we must never lose sight of our true source of standing. . .our focus should be on empowering our members and meeting their needs.

Activating Member-Owners

People’s voices and votes are the ultimate power in a democracy.  The first call to action with members should be in the upcoming annual meetings. To make this event a rallying cry, the traditional approach must be rethought. However,  this is not a new challenge.

In March 2023 Silicon Valley and two other banks failed in quick succession as the  Federal Reserve increased interest rates.  Many credit unions instantly changed their meeting’s  scripts.  In one I attended, the CEO after summarizing the prior year’s performance, pivoted to explain why her credit union and the industry generally did not have similar problems.

The message was to assure members their funds were safe.  Do nothing and trust your credit union.

This time the message is quite different. The  challenge is to educate members about changes being considered and ask them to act, not just stay the course.  Member-owners contacting their congressional representatives, en masse, is the most powerful influence on political behavior.

1998-The Year of Member Action

In 1998 the Supreme Court ruled in favor of a banking challenge to changes NCUA made in its field of membership regulations in the early 1980’s.  If implemented, the decision would have limited credit unions to their original, or a single, field of membership.  The law the Court interpreted had to be changed and fast.

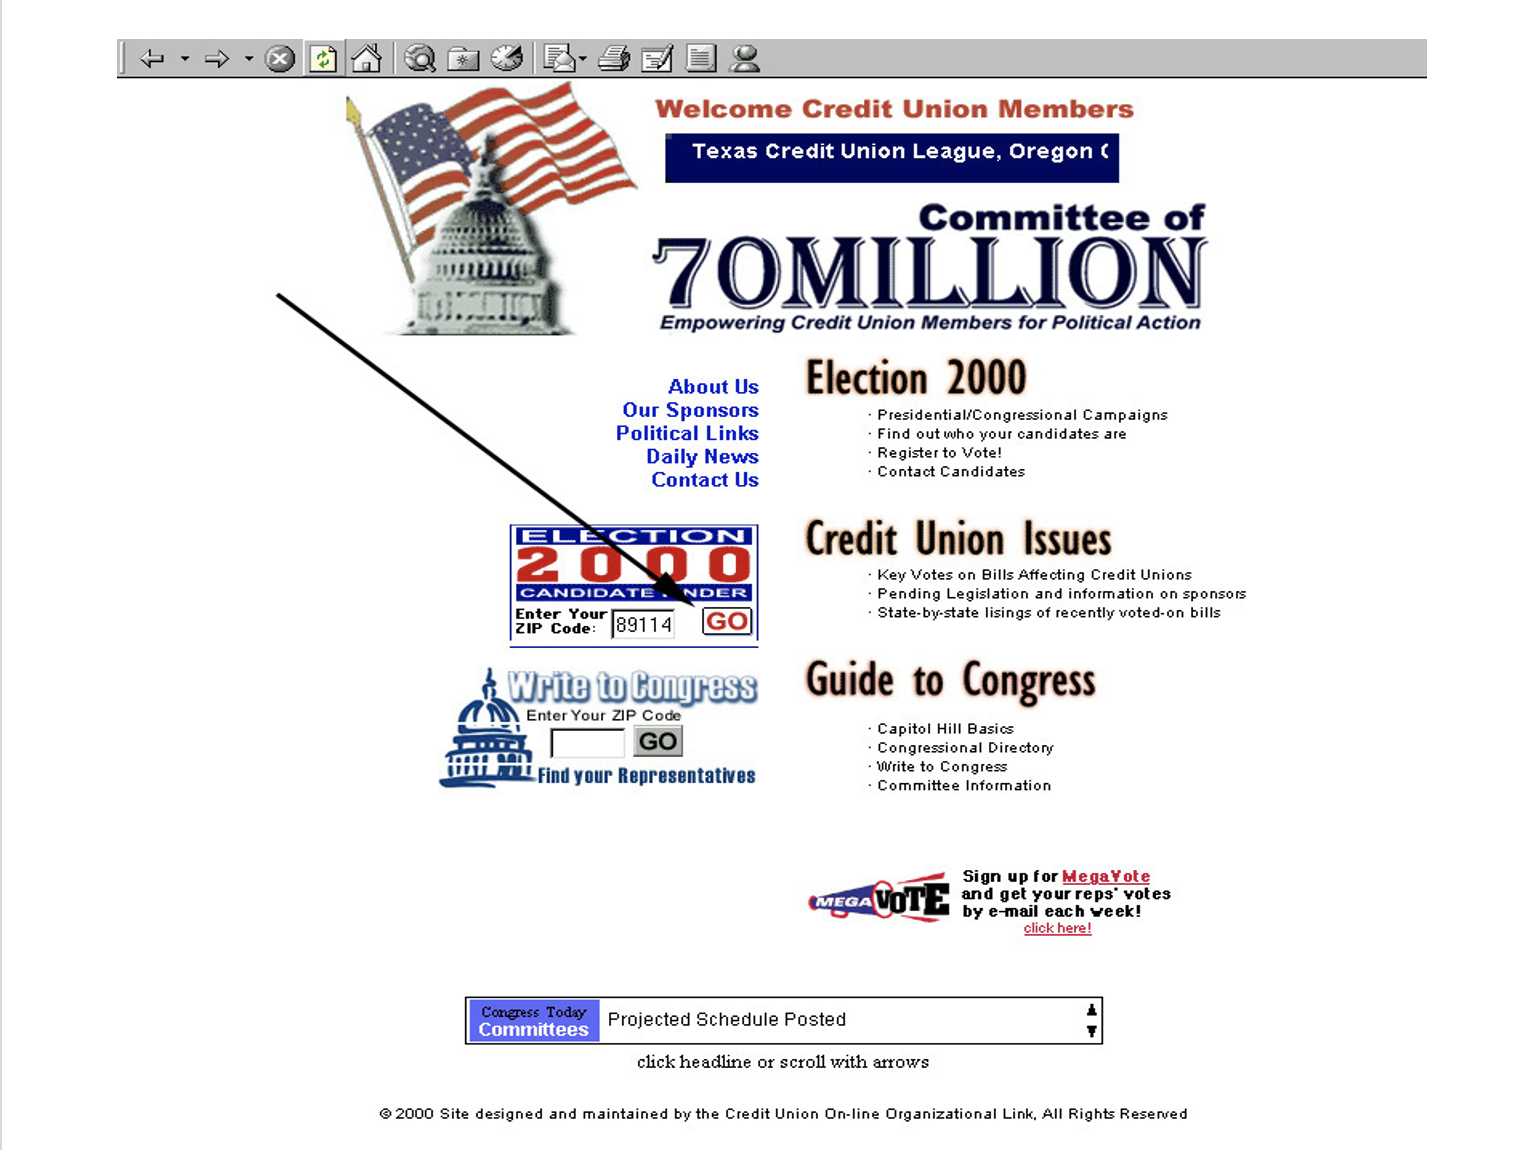
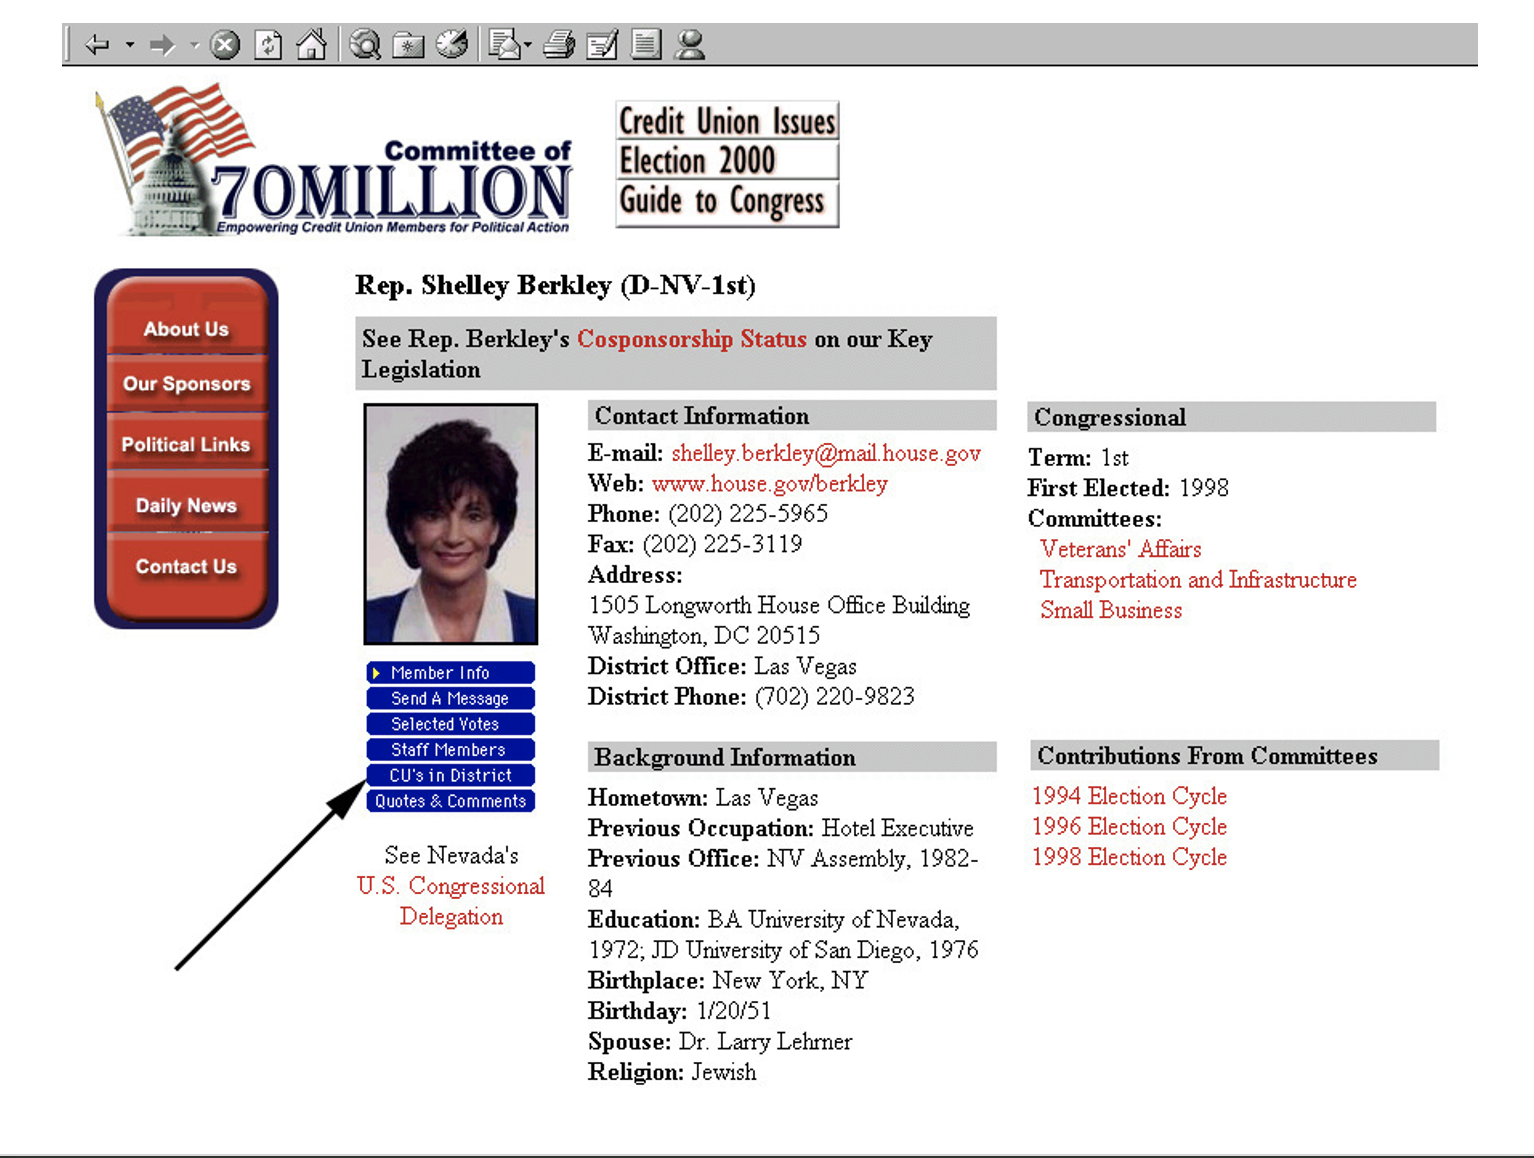
One of the means to both engage and empower members was a newly created website called The Committee of 70 Million. The name was an echo of Revolutionary War grass roots organizations.

It was created by Scott Patterson, a recently hired techie at Callahan & Associates.  Although the country and credit unions were in an early phase of the Internet era, with social media still unknown, this platform could be linked to every credit union on the Internet.

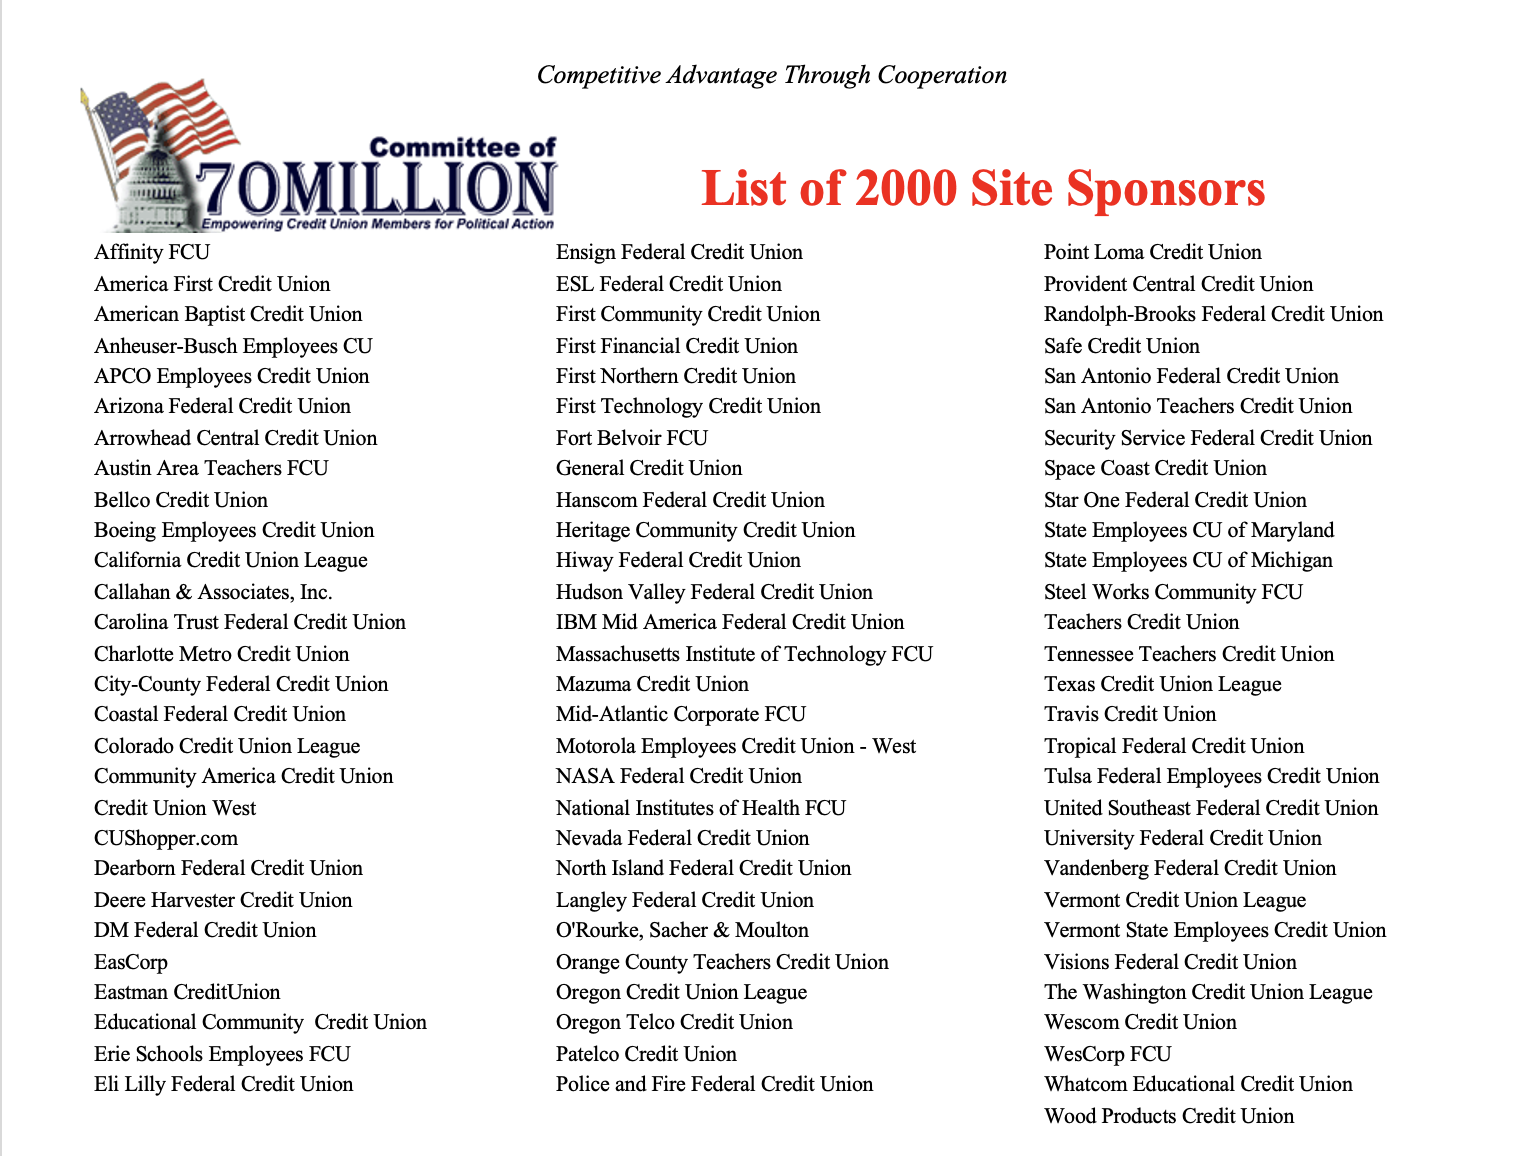
The site explained the what was at stake and suggested multiple ways members could reach out to their congressional representatives.  Here are six slides from a much longer review in 2001 of the site’s options, information and impact.

The site was then adapted for voting in the Presidential election year 2000.

The Status Quo Is No Longer

Trump promised total disruption of the federal government bureaucracy.  He is on course. Now is the time for mobilizing member-owners.

The annual meeting should be converted to a town hall format. This is an opportunity to connect and  inform about the political changes.  The members’ questions and reactions can be used to plan next steps. After all, it is likely 50% or more voted for Trump’s message.

Credit unions must gain members’ respect and trust for the steps you will propose.  The most important message however,  is that this is not just another political fire drill.

Note: To receive the full slide deck, contact Scott Patterson at spatterson@gmail.com.


The Source of Credit Union Power: Members Rally to Rebut Banker’s “Hit” Article

“You will pry my credit union from my cold middle class dead hands.”   Words of defiance from a credit union believer. One of hundreds of comments posted last week.(source below)

A leader’s ultimate success much depends on how the person manages the instruments of power.  For some in authority, the point of power is to use it to expand one’s dominion.  Using requires building up an institution’s size, scope of activity and resources to control or dominate.

However, there is another leadership model.These individuals believe that the role of authority is empowering others.  Credit unions at their most effective are subversive of status quo structures. They organize from the bottom up.  By the grass roots, not by investors hoping to make money.  No capital, just personal sweat equity, time and collaborative effort to accomplish common purpose.

This counter-cultural, not-for-profit cooperative design is also the key to  credit unions’ latent political power.  Here is a case study from last week of what this looks like in practice.

Responding to a Newspaper Opinion

Last week the Washington Post published an Opinion article by the former chair of the FDIC, Sheila Bair, titled:   Tax-free credit unions are thriving at public expense.  Her bank in Chesterton, MD, The Peoples Bank, accepted a purchase offer from a Massachusetts credit union “using some of their untaxed income.”

Her article referenced other examples of credit union branding and expansion.  Her recommendation was to level the playing field with community banks by taxing credit unions.  Otherwise, she warned, ““Give them an inch and they’ll take a mile.”

I had used the credit union’s purchase of “her” bank as an example in a blog Time to Ask WHY.  My p;oint was to illustrate the bigger public stage on which credit union actions are now viewed.

I did not foresee the  Post’s readers’ reaction to her article.   When the postings were stopped 253 comments had been submitted, almost all from credit union members.

The members universally defended their credit unions, called the article a “hit” piece, and provided hundreds of firsthand examples of how credit unions provide special member value.

Following are a few examples of the readers’ responses unleashed by this former banking regulator’s critique of credit union’s tax status.

From a bank customer and credit union member:

I have business both with a major bank and a credit union-right now the rate on my major bank credit card is 27.99% (they cut my rate a whopping 2% from 29.99% a few months ago!)

Right now, the rate on my credit union credit card is 8.99%

 You can probably surmise from the above anecdote who gets most of my business… 

From a 30 year member::

I have been a credit union member for 30 years. No hidden fees, low interest credit card, interest on my checking and savings, no service charges, talking to real people, great service, the list goes on and on. I would prefer to never have to deal with a bank again. I’m sure big banks would love to crush credit unions.(Reader comment ratings:  Provocative/Thoughtful 61)

From a member with mortgage loans for 37 years;

I’ve had a mortgage since 1988 on my successive residences, usually with an escrow account to pay property tax and homeowners insurance. Refinancing in 2012 with a credit union was the first time I managed to persuade my lender to include California Earthquake Authority premiums in the escrow account associated with my mortgage.

I’ve been much more satisfied with the service I’ve received from a credit union than from any of the big banks I’ve patronized over the years…. 

A Question posed: The difference, who cares more about you?

Ask yourself a simple question. WHO cares more about YOU as an individual? A big bank or the credit union where you are a member?

Notice that YOU are a member of the credit union – not just a customer. With banks – YOU are just another income source.

A question: Why the article?

Of all the non-profits that exist (and ALL credit unions are non-profit) – why attack the one group that actually takes care of their members instead of pushing propaganda as part of a political agenda?

 Attacking the for-profit Washington Post:

Wow, taking a shot at non-profit banking!?!? Proof once again that the Post is in the bag for corporate interests. Where is the guest opinion on the mis-deeds of for profit banks? Instead of recommending that credit unions return to stricter membership rules, or limit their ability to purchase commercial banks, you go right for their non-profit status. I have not used a for profit bank in 25 years. Thankfully almost everyone on Capitol Hill banks with the Congressional Federal Credit Union (as do I) so they understand the value of a credit union. 

A comment on the Opinion author:

As others have pointed out, Shelia Bair was chair of FDIC during the 2008 financial meltdown. She was a major architect of the TARP bailout of Chase, Bank of America, Wells Fargo, and the other big banks. 

This is an unadulterated hit piece against Navy Federal Credit Union, which is competing with the big banks directly in their consumer banking business. 

How and When Is Member Power Mobilized?

The comments extend for another 240+ reader reactions.   These words are not lobbying jargon, irrelevant numbers or cliches.   They are from lived experience motivated by personal feelings.

Implicit in these words is a readiness for action.  This potential  is the real source of credit union power, not the amount of PAC dollars donated.  It is the member-owner-voter’s relationship with their credit union.

This foundation of the movement is a latent,  “sleeping giant”-a phrase used by Ed Callahan during the 50th anniversary of the FCU Act in 1984 and afterwards.  Deregulation had placed  the responsibility for the future of credit unions back where it started, in the hands of boards and members, not the federal government.

The Immediate Challenge

America is in an era of political disruption. The issue of taxation will undoubtedly arise in several contexts.  But the real challenge of crafting a new beginning, a rethinking of who we want to be, is much greater.  And it may be beyond the grasp of those who seek only to defend the existing co-op status quo.

What is necessary are new models to tackle critical opportunities for clarity about credit unions’ future role in the American economy and members’ lives.

The country is hungry to reset foundations, recommit to fundamental values and for new generations of leaders who can innovate with cooperative design.

We should avoid marketing our fear of change to garner internal support, but rather take this fluid moment to rally our members for a renewed vision of what we can be.

And like the initial founders, or the change makers who led deregulation, this new era can be both frightening and enlightening.  This redesign may involve both government/regulatory relationships and new realities for industry participants taking  responsibility for our future.  It may entail new organizational relationships and partnerships.

If one looks closely the seeds for a new future are already there.  Some have been planted by those seemingly old school; others are in the enthusiasm of a generation that seeks to change the world.  Our skill will be to identify those whose directions empower others with their vision, versus those intent on enhancing their existing legacy returns.

Let the conversations begin.   If you have any doubts about what members value, just go the article and read some of the several hundred more comments.   The members’ voice is there if we really listen.